How to Conduct a Materiality Assessment for ESG Reporting: A Practical Business Guide
Quick Answer
A materiality assessment identifies the environmental, social and governance matters that deserve priority in a company’s strategy and reporting. A credible process examines business context, actual and potential impacts, financial risks and opportunities, stakeholder evidence and reporting requirements. The result should be approved by senior leadership, supported by records and linked to clear actions, metrics and responsibilities.
A sustainability report can contain dozens of indicators and still avoid the issues that matter most. This usually happens when the reporting team starts with a template rather than the business.
Energy, employee wellbeing, water, supply-chain labour, data privacy and climate risk may all be relevant, but their importance depends on the organisation’s sector, locations, business model and value chain. A materiality assessment provides the discipline needed to choose priorities. For UAE and GCC organisations, it can inform reporting, ESG strategy, investor responses and tender submissions, provided the method matches the intended framework and audience.
What Is a Materiality Assessment?
A materiality assessment is a structured process for identifying and prioritising sustainability matters that are significant to an organisation and its stakeholders.
The meaning of “material” depends on the framework. GRI 3 defines material topics as those representing an organisation’s most significant impacts on the economy, environment and people, including human rights.
IFRS S1 applies an investor-focused form of financial materiality. Information is material when omitting, misstating or obscuring it could reasonably influence decisions by users of general-purpose financial reports. It covers sustainability-related risks and opportunities that could affect cash flows, access to finance or cost of capital.
The European Sustainability Reporting Standards use double materiality. This considers both the organisation’s impacts on people and the environment and the financial effects of sustainability-related risks and opportunities on the organisation. EFRAG notes that there is no single methodology suitable for every company; the process must reflect the organisation’s circumstances and use supportable evidence.
A company should therefore confirm the reporting basis before designing its assessment. Combining different definitions without explaining the method can produce a result that looks sophisticated but is difficult to defend.
Why Materiality Matters Beyond the ESG Report
The immediate output is a prioritised topic list. The more valuable outcome is better management information. A sound assessment can reveal overlooked dependencies, changing customer expectations, emerging commercial risks and gaps between public commitments and internal capacity.
For a hypothetical UAE food manufacturer, water, packaging waste, worker welfare and energy may all require assessment. The process provides a documented basis for deciding which matters are most significant and how each should be managed and reported.
Where appropriate, elementsix can support this work by connecting ESG topics with measurable environmental impacts, emissions data, operational evidence and practical reduction opportunities.
Step 1: Define the Purpose and Reporting Basis
Start by agreeing why the materiality assessment is being conducted.
The objective may be a GRI report, an ESG strategy, investor disclosure, parent-company reporting, tender readiness or preparation for future requirements.
Document the framework, entities, facilities, value-chain boundaries, time horizons, intended users and approval responsibility. An investor-focused exercise may emphasise enterprise prospects, while an impact-focused assessment considers effects on people and the environment.
Without this foundation, later scoring discussions become inconsistent.
Step 2: Understand the Organisation’s Context
Build a clear picture of the business before creating a topic list. Review products, services, locations, workforce, suppliers, customers, assets, technologies and regulatory exposure. Consider how the company depends on energy, water, ecosystems, labour, infrastructure and community relationships.
Useful evidence may already exist in risk registers, permits, incident records, employee surveys, customer requests, procurement audits, emissions data, grievance records and board papers.
Sector standards and peer reports can identify topics that may have been missed, but they should not determine the final result. Another company’s priorities reflect its own operations and judgement.
Step 3: Identify Impacts, Risks and Opportunities
Create a long list of sustainability matters based on evidence rather than preference.
For impact materiality, examine actual and potential positive and negative effects across activities and business relationships. Negative impacts are generally assessed by severity; potential negative impacts also require consideration of likelihood.
For financial materiality, assess possible effects on revenue, costs, assets, liabilities, financing, business continuity and strategy.
One topic may be significant through both lenses. High energy consumption creates environmental impacts through greenhouse-gas emissions and may also expose a company to price volatility, efficiency losses or changing customer requirements.
The review should extend into the upstream and downstream value chain where relevant. Focusing only on direct operations can miss significant issues in purchased goods, logistics, product use, disposal and contracted labour.
Step 4: Engage the Right Stakeholders
Stakeholder engagement should inform the assessment, not replace analysis.
Relevant groups may include employees, customers, suppliers, investors, regulators, affected communities, industry bodies and subject-matter experts. The appropriate mix depends on the organisation’s impacts and reporting purpose.
Surveys are efficient but often shallow. Interviews, workshops, grievance data and targeted discussions usually provide better context. Ranking a generic topic list may reveal preferences, but it does not establish materiality by itself.
Record who was consulted, why they were selected, what evidence they provided and how conflicting views were handled.
Step 5: Assess Significance and Set Thresholds
Scoring can make decisions more consistent, but the numbers should not create false precision.
Impact criteria may include scale, scope, irremediable character and likelihood. Financial criteria may include magnitude, likelihood and time horizon. Each score needs a rationale and evidence reference.
The organisation must also define the threshold used to determine which topics are material. GRI advises organisations to rank impacts and document the cut-off used for reporting. Difficulty in collecting data or the absence of an existing policy is not a valid reason to declare a significant topic immaterial.
A materiality matrix can communicate results, but it should not be treated as the assessment itself. Written explanations, priority tables and evidence records are often more useful than a single two-axis chart.
Step 6: Validate and Approve the Results
Test the proposed topics with internal leaders, relevant experts and selected stakeholders. Ask whether significant impacts have been omitted, whether scoring is supported and whether the final list reflects the chosen reporting framework.
GRI recommends that the highest governance body review and approve the material topics, or that senior executives do so where no such body exists.
Approval should not be ceremonial. Decision-makers need to understand the method, key judgements, limitations and implications for strategy, targets and disclosure.
Step 7: Turn Material Topics Into Management Priorities
A materiality assessment is incomplete if the result remains in a presentation.
For each material topic, assign an accountable executive and operational owner. Define relevant policies, actions, metrics, baselines, targets, data sources, resources and review dates.
Some topics need technical measurement before credible targets can be set. Climate may require a greenhouse-gas inventory, water may need facility-level metering, and workforce topics may require better data.
elementsix can help organisations link material environmental topics with carbon footprints, reduction roadmaps, ESG governance and credible reporting. The aim is to establish priorities that can be measured and managed, not simply to produce a longer list of commitments.
Common Materiality Assessment Mistakes
The first is treating stakeholder popularity as materiality. A frequently selected issue may be important, but significance must still be assessed against the relevant framework.
Another is beginning with a predetermined list designed to confirm management’s existing priorities. This can exclude uncomfortable matters such as supply-chain practices, environmental claims or weak data controls.
Some companies combine positive and negative impacts into one score, allowing a positive initiative to cancel out a serious negative impact. GRI states that negative impacts cannot be offset by positive impacts when determining material topics.
Other weaknesses include unclear boundaries, undocumented thresholds, reliance on peer reports and failure to consider the value chain. Review the assessment after acquisitions, new markets, major projects, incidents or regulatory changes.
Materiality Assessment Checklist
Confirm the purpose, audience and reporting framework.
Define entities, operations, value-chain boundaries and time horizons.
Review business, sector, regulatory and stakeholder evidence.
Identify actual and potential impacts, risks and opportunities.
Select stakeholders according to relevance and degree of impact.
Apply documented criteria and scoring rationales.
Set and record the materiality threshold.
Validate the results with management and relevant stakeholders.
Obtain board or senior-executive approval.
Assign owners, actions, metrics and review dates.
Retain evidence supporting assumptions and judgements.
Review the assessment after significant business changes.
Frequently Asked Questions
How often should a materiality assessment be updated?
There is no universal interval. Many companies complete a full reassessment every two or three years and review topics annually. Update it earlier after an acquisition, significant incident, regulatory change, new market or major business-model change.
Is a stakeholder survey enough?
Usually not. Combine survey findings with operational data, risk information, regulatory review, expert judgement and evidence about actual or potential impacts. Stakeholder opinions inform materiality but do not replace the organisation’s assessment.
What is the difference between financial and impact materiality?
Financial materiality considers sustainability-related risks and opportunities that could affect the organisation’s prospects and influence investor decisions. Impact materiality considers the organisation’s significant effects on people, the environment and the economy. Double materiality examines both perspectives and the connections between them.
Does every material topic need a target?
Not immediately. A company may first need better data, a baseline or a feasibility assessment. It should still explain how the topic is managed, who is responsible and what will happen next. Targets should be specific and evidence-based rather than announced before the organisation understands its starting point.
Can an SME conduct a materiality assessment?
Yes. The process can be proportionate to the company’s size and complexity. An SME may use focused interviews, existing business records and a concise scoring method rather than a large consultation exercise. Clear boundaries, relevant evidence, documented judgement and management ownership remain important.
From Material Topics to a Credible ESG Programme
A useful materiality assessment gives management a defensible view of the impacts, risks and opportunities requiring attention. It begins with business context, applies the correct definition of materiality and retains evidence for significant judgements. Once priorities are approved, responsibilities, data, targets and investment decisions should follow.
elementsix supports UAE and GCC organisations with practical ESG materiality assessments, greenhouse-gas accounting, sustainability strategy, reduction planning and credible disclosure. To discuss a materiality assessment or ESG reporting project, email [email protected], visit www.element6.cc, or submit an enquiry through the official website. The company’s headquarters are at DTEC, TechnoHub Building 1, Dubai Silicon Oasis, Dubai, United Arab Emirates. The official contact page does not currently publish a telephone number.
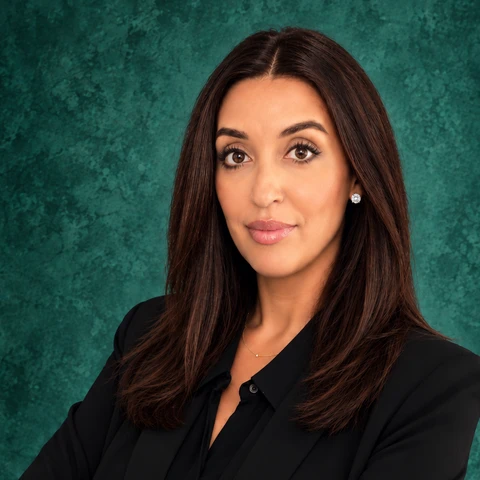
Dahlia Haleem
Dahlia Haleem, co-founder and partner at elementsix, is an emission reduction expert with a strong background in physics and engineering. She has over 15 years of valuable experience in project management, strategic advisory, sustainability and carbon management across MENA and APAC.
View all articles by Dahlia